LIV Golf Shuts Down Operations After $300 Million Rescue Deal Collapses
The Saudi-backed league will liquidate instead of launching LIV 2.0 in 2027.
KEY POINTS
- LIV Golf is liquidating instead of launching LIV 2.0 in 2027
- BC Partners abandoned a $300 million rescue investment
- The league filed for Chapter 11 bankruptcy on September 8, 2026
- Jon Rahm forfeited about $100 million in claims to exit his contract
- LIV paid $15.6 million to retain seven executives, including $6.375 million to CEO Scott O'Neil
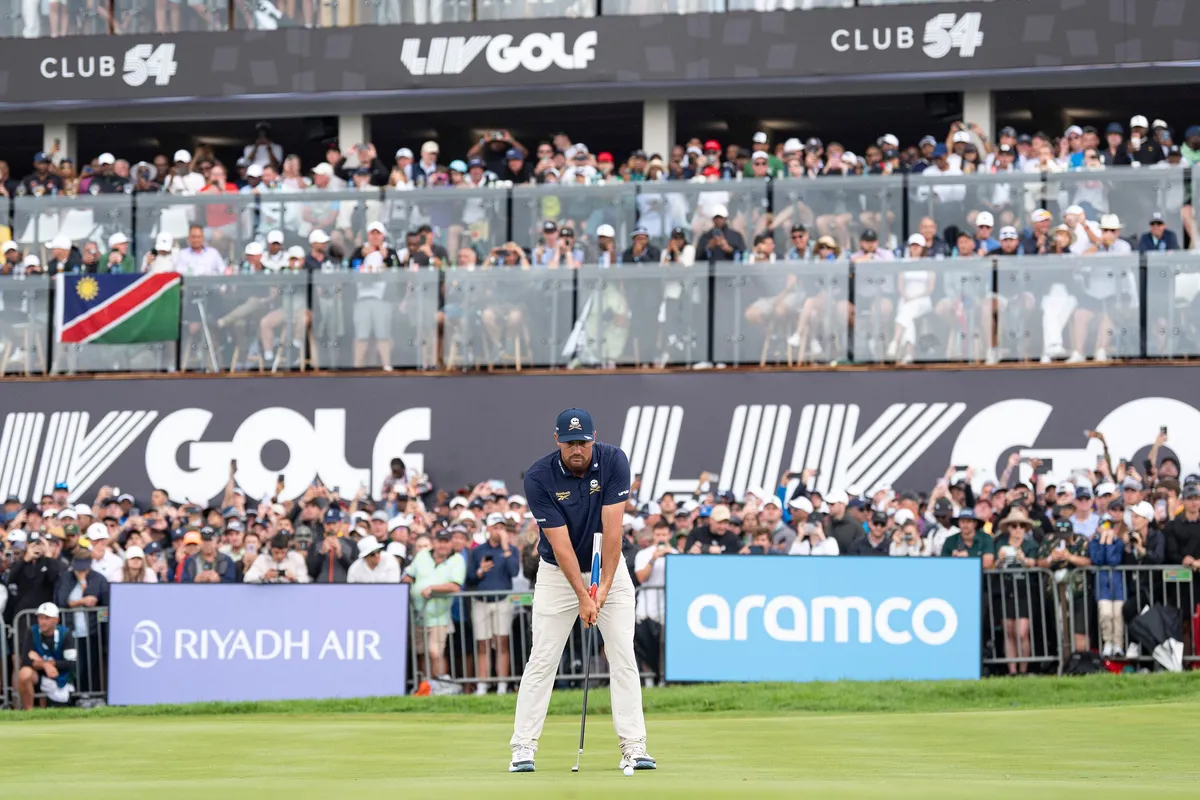
LIV Golf is winding down operations after five years that fractured professional golf. The Saudi-backed circuit announced the decision in a New Jersey bankruptcy hearing on Thursday, November 5, 2026.
The shutdown follows the collapse of a proposed $300 million rescue deal from BC Partners Credit. The investment was intended to support a restructured LIV 2.0 league planned for the 2027 season.
“The debtors are not currently proceeding with the LIV 2.0 plan. Instead, the debtors are toggling to a value-maximizing wind-down in their business.”
LIV Golf filed for Chapter 11 bankruptcy on September 8, 2026, after losing Saudi Arabia funding in April. The league had spent more than $5 billion since launching in June 2022 with nine-figure signing bonuses to attract top players away from the PGA Tour.
Players including Jon Rahm, Sergio Garcia, Tyrrell Hatton, and Louis Oosthuizen were not interested in the LIV 2.0 plan. About 15 players had previously committed to the restructured league, according to earlier reporting.
Rahm agreed to forfeit all claims against LIV, said to be worth some $100 million, to exit his contract. He has returned to playing the European tour, which currently imposes a one-year ban dating to players' last LIV appearance.
LIV Golf paid $15.6 million to retain seven executives between the Public Investment Fund withdrawal and the bankruptcy filing. That amount included $6.375 million to CEO Scott O'Neil. It remains unclear whether those payments can be voided now that liquidation is proceeding.
BC Partners said it supported a transaction aligning player and investor interests but could not reach mutually acceptable terms with stakeholders.
2 more sources below
COMMENTS (0)
No comments yet. Be the first.
RELATED STORIES
Turkey caps ownership transfers at 49 percent in industrial zones
New regulation bans speculative land transfers and requires electronic signatures for workplace permits in organized industrial zones.
Greece signs deal for new 600-inmate prison in Megalopolis
Prime Minister Kyriakos Mitsotakis attended the signing of a 40-million-euro prison project in Megalopolis on Thursday.
Adipec 2026 opens in Abu Dhabi with record 239,000 participants
The four-day energy conference brings together global leaders, ministers and executives to discuss energy security, AI and infrastructure investment.
- New York Times Sues Brave Over Copyright and AI Content Use
- Brazil court blocks Meta from using news content for AI training
- Cristiano Ronaldo retires from Portugal national team after 23 years
- Paris Jackson seeks $600 million from father's estate after 17-year wait
- David Jones Enters Administration as Suppliers Remove Stock
This page was compiled with AI assistance from the outlets named above and passed an automated language check before publication. Montegre has no reporters of its own; the byline names the outlets the story was compiled from. Method and editorial standards