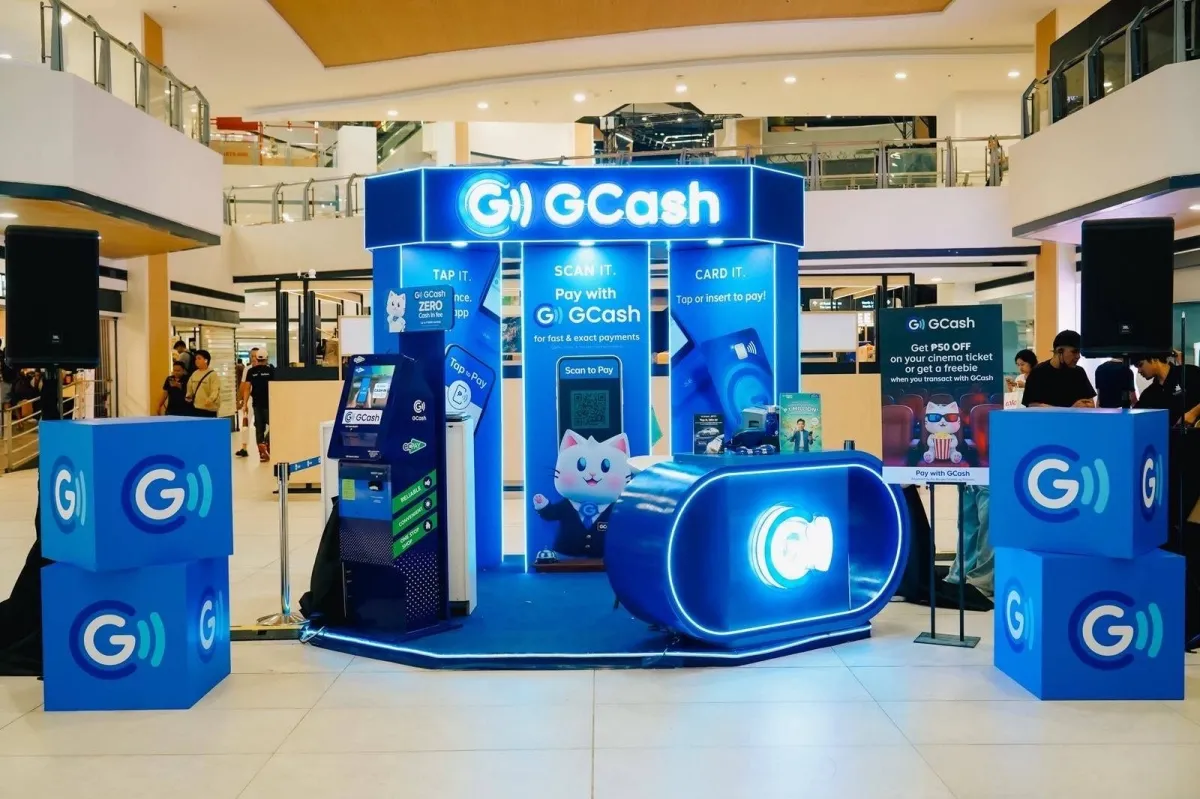
Mynt prices GCash IPO at P6.60, aims to raise up to P60.9B
Philippines' largest tech listing prices 34% below initial range as investors demand discount amid valuation concerns.
KEY POINTS
- Mynt prices GCash IPO at P6.60/share, 34% below the P10 ceiling
- Base deal of P53B could reach P60.9B with overallotment, becoming largest PH IPO
- Anchor investors committed P36.5B before public offer opens
- Valuation at P442B implies 25.6x trailing earnings; analysts flag credit risk
- H1 2026 net income grew only 7%; EBITDA fell 4% as margins compressed
Mynt, the parent company of mobile wallet operator GCash, has set its initial public offering price at P6.60 per share, confirming a significant discount from the earlier P10 ceiling. The company plans to sell up to 8.03 billion primary shares, potentially raising P53 billion, with an overallotment option for 1.2 billion additional shares that could lift total proceeds to P60.9 billion.
If fully subscribed, the deal would surpass Monde Nissin's 2021 listing to become the Philippines' largest-ever IPO. Large investors have already committed to purchasing P36.5 billion worth of shares ahead of the public offer, according to the preliminary prospectus.
“At P6.60, GCash/Mynt is less stretched than the original P10 range, but we wouldn't call it cheap.”
At the offer price, Mynt carries a market valuation of roughly P442 billion, or 25.6 times trailing earnings, down from the P669 billion implied at P10. Analysts note the 34% reduction reflects market pushback driven by a weak peso, inflation concerns, and the unresolved US-Iran conflict.
DragonFi Securities analyst Jarrod Tin said the valuation is "less stretched" but not cheap, flagging credit quality as a key risk as provisions already account for 44.1% of CreditTech revenue. Mynt's public float of 12.06% to 13.86% also remains below the 15% threshold for PSE index inclusion.
Financial results show the business entering a more mature phase. Net income rose just 7% year-on-year to P10.82 billion in the first half of 2026, while core operating cash earnings (EBITDA) dipped 4% to P11.76 billion and operating margins tightened from 31.3% to 27.3%.
A lock-up expiration around April 18, 2027, could make about two-thirds of shares eligible for sale, presenting a further consideration for investors.
2 more sources below
COMMENTS (0)
No comments yet. Be the first.
RELATED STORIES
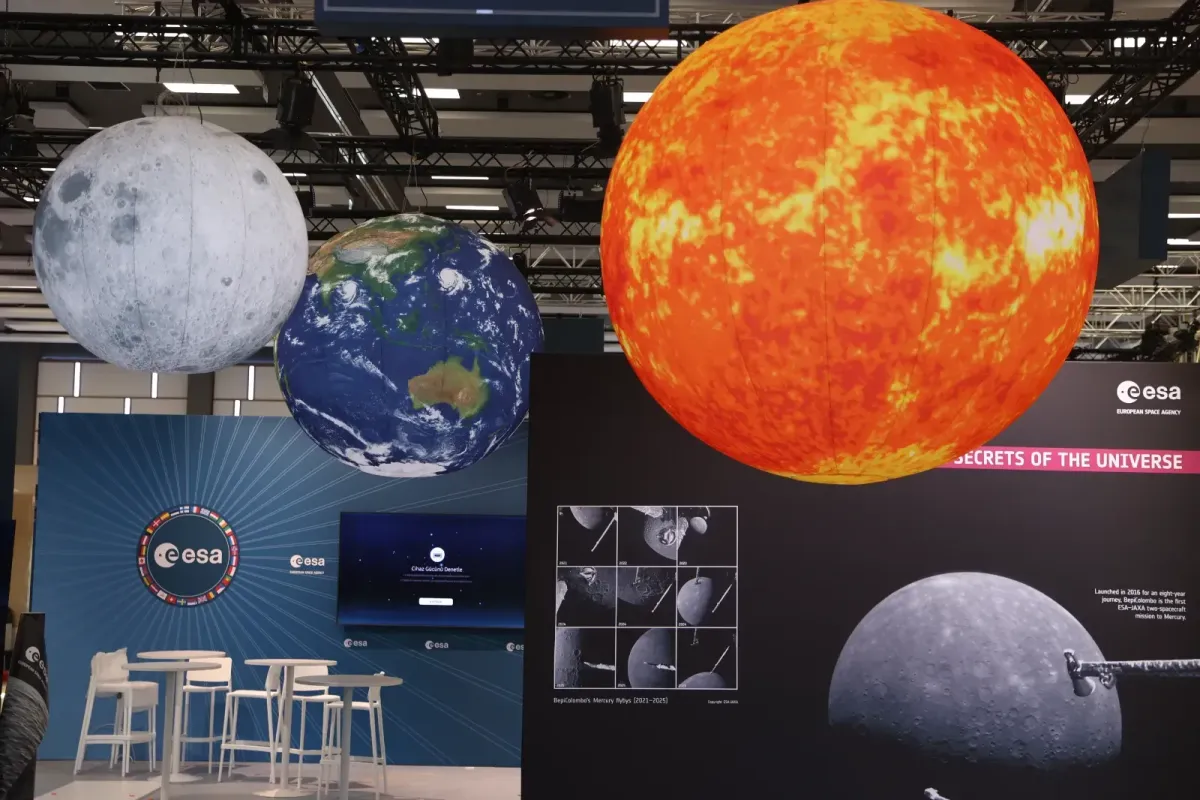
Turkey Hosts 77th International Astronautical Congress in Antalya
Minister Kacir announces 2027 moon mission with 87% domestic spacecraft as 12,000 delegates from 111 countries gather.
20 Suspects Referred to Court in Capital Markets Fraud Probe
Prosecutors seek detention for 20 suspects in an investigation into alleged market manipulation and fraud, raising total detainees to 85.
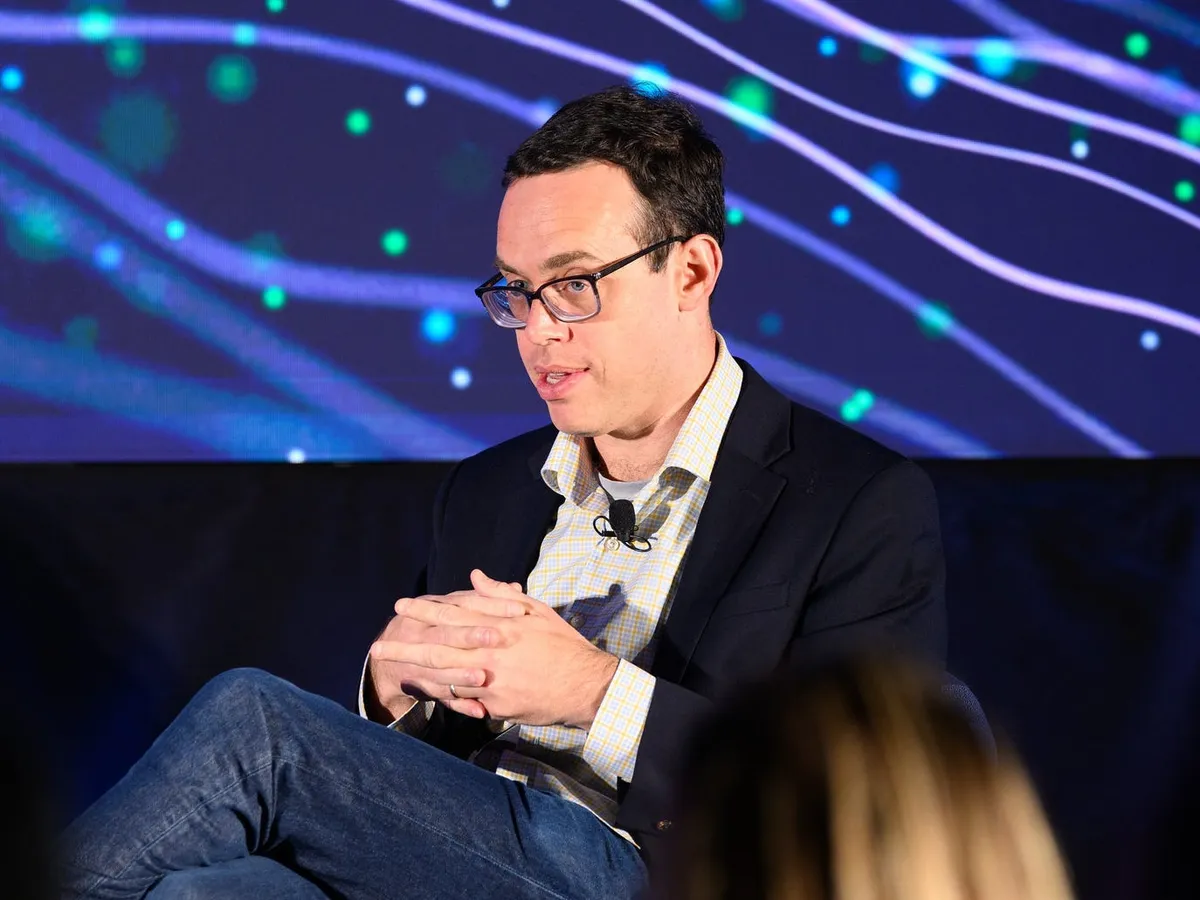
Ex-OpenAI Safety Lead Warns AI Firms Not Careful Enough
David Robinson says companies prioritize speed over safety and calls for external incentives to slow development.
This page was compiled with AI assistance from the outlets named above and passed an automated language check before publication. Montegre has no reporters of its own; the byline names the outlets the story was compiled from. Method and editorial standards